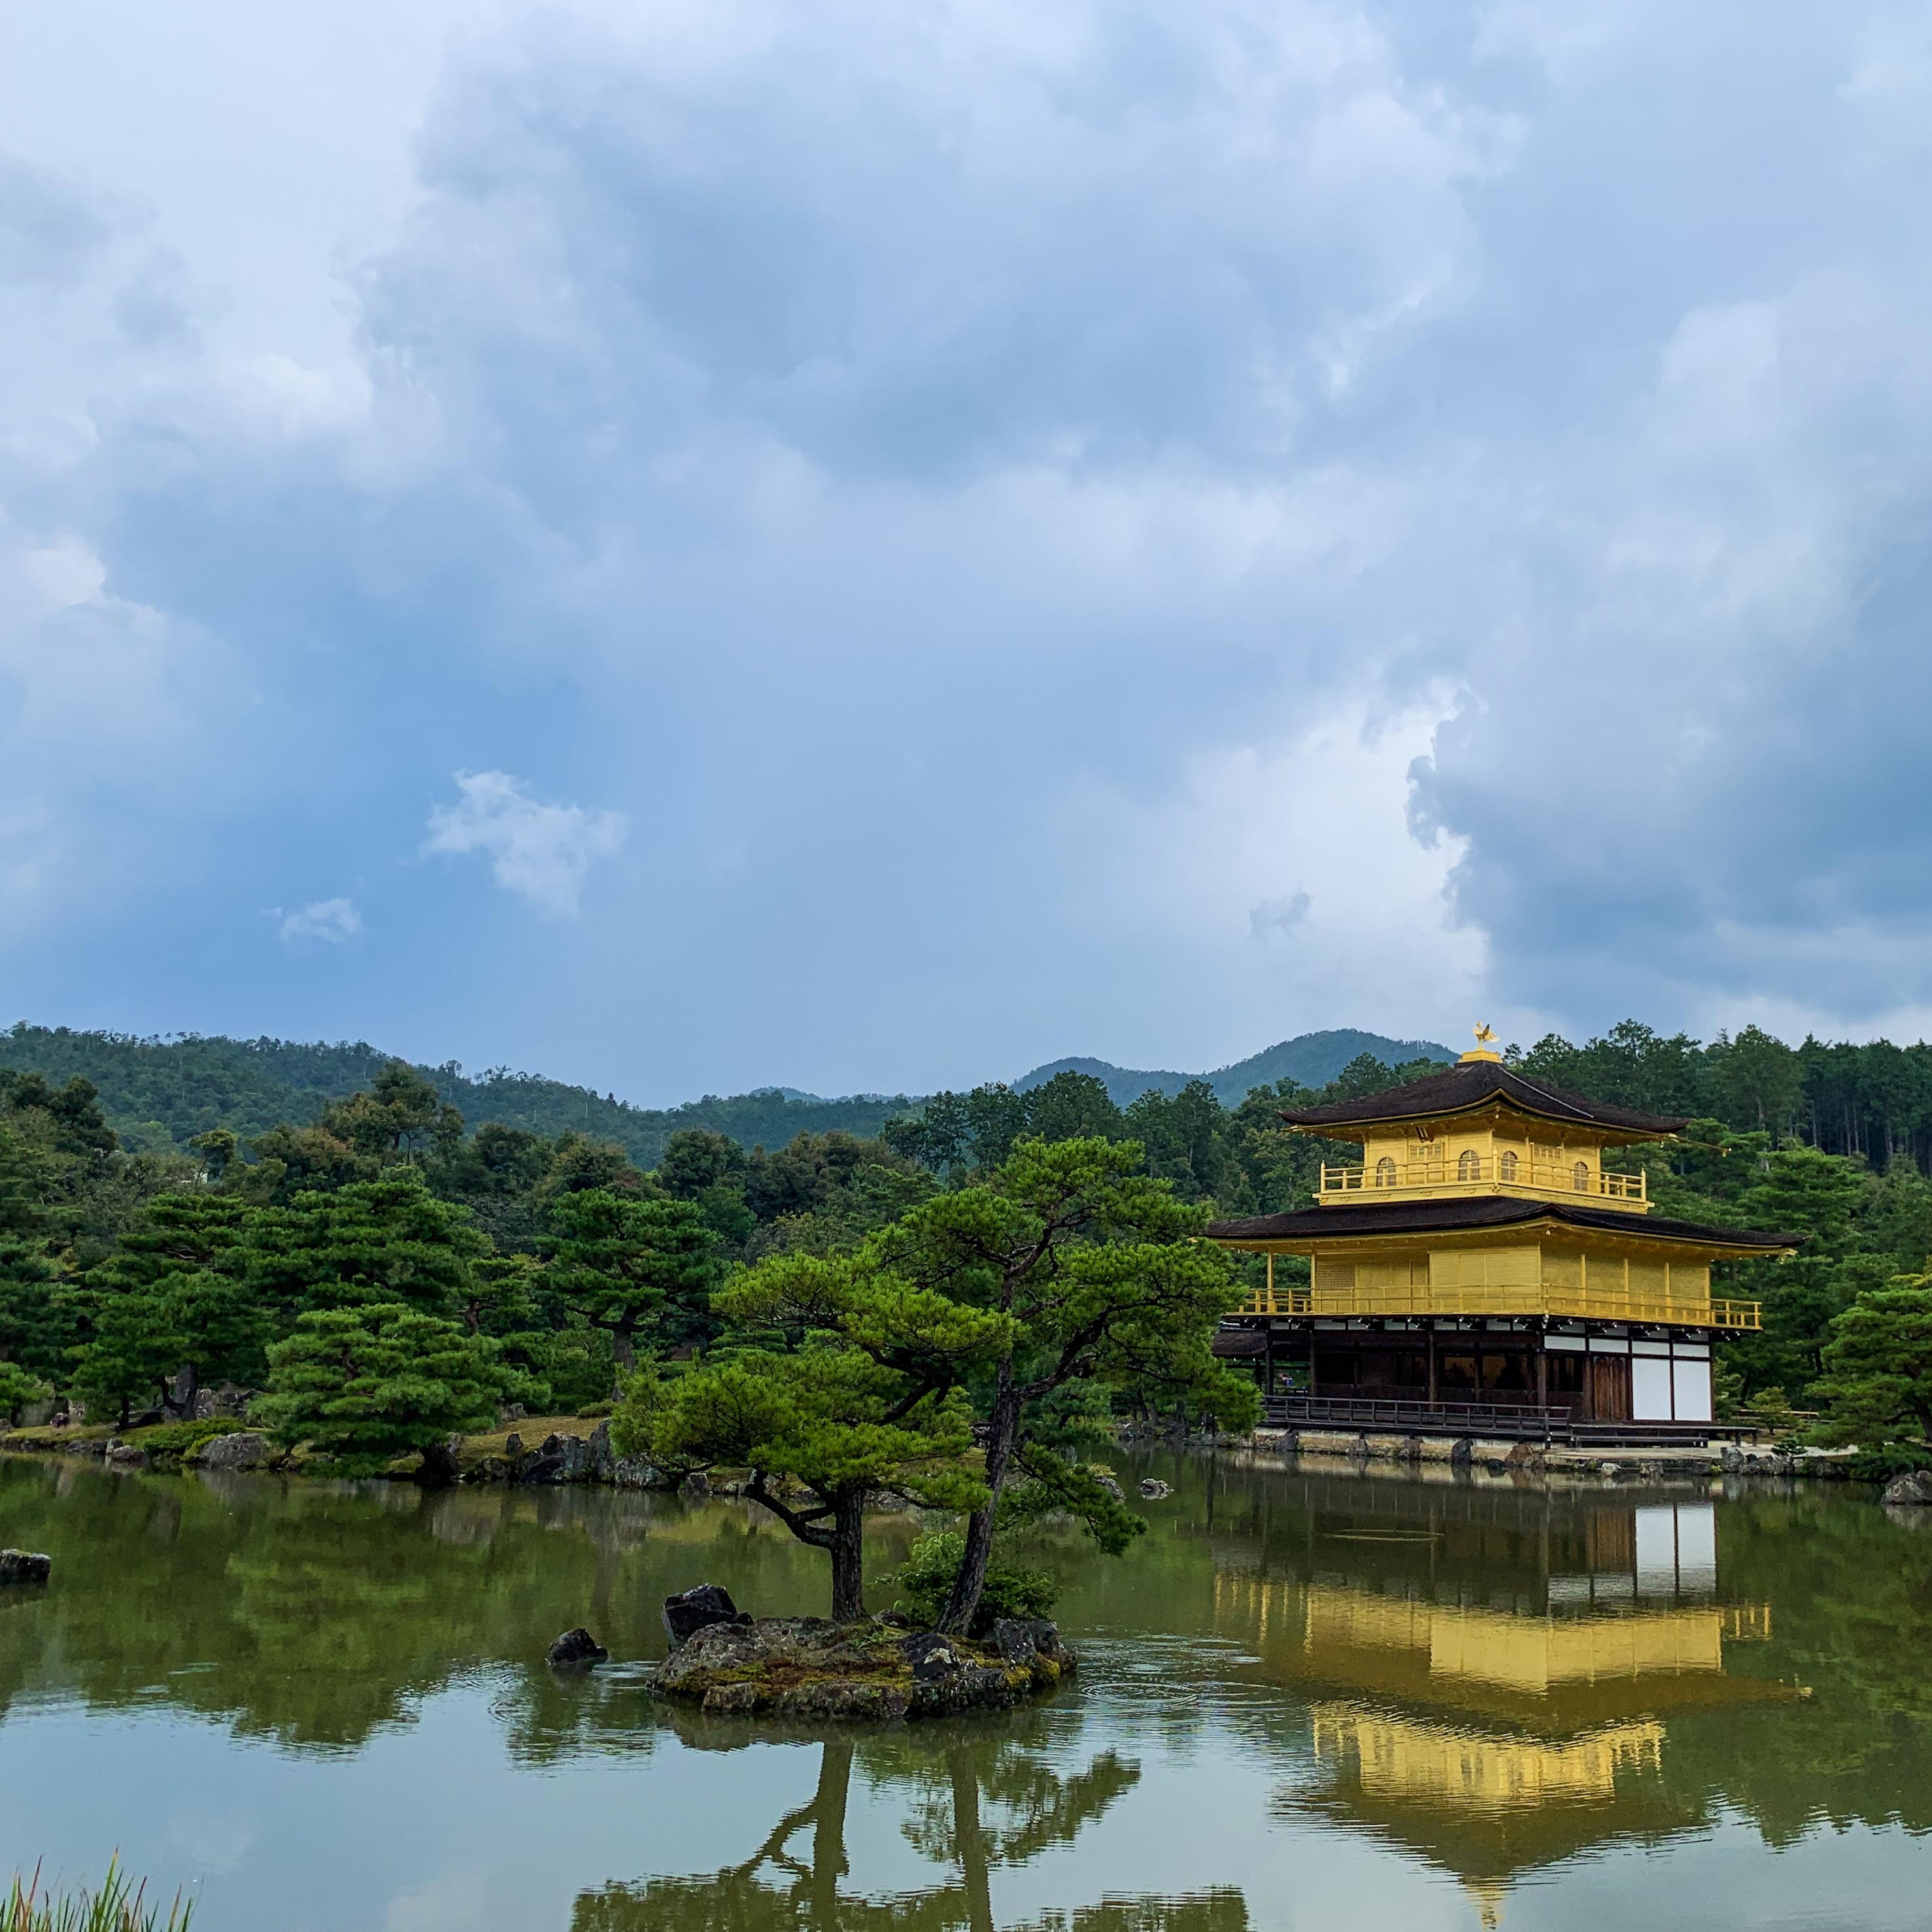
I just got back from Japan. Mount Fuji, Kyoto temples, Tokyo street food at 2am — it was everything I hoped it would be. Travel like this doesn't happen by accident. It takes intention, planning, and a financial foundation that lets you say "yes" when the opportunity arises.
Over the years, I've worked with hundreds of clients who want to build a financial life that includes experiences like this. And without fail, the conversations that matter most come down to two things: the one financial goal every person needs, and the one risk every person needs to protect against.
These aren't flashy. They're not as exciting as talking about index funds or early retirement. But they are the foundation of every solid financial plan. Get these right and everything else becomes easier.
The One Goal: Your Emergency Fund
🎯 The Goal: 3–6 Months of Expenses in Cash
An emergency fund is a dedicated savings account containing enough cash to cover 3 to 6 months of your essential living expenses — housing, food, utilities, transportation, minimum debt payments, and the like. This money sits in a high-yield savings account, untouched, until you truly need it.
I know what you're thinking. "Riki, I have a stable job, great health, and I'm young. Why do I need to lock up that much money doing nothing?"
Because life is wildly unpredictable. And when something goes wrong — a job loss, a medical bill, a car engine that gives up the ghost — the difference between a minor inconvenience and a financial catastrophe is often one thing: cash on hand.
When you don't have an emergency fund, unexpected expenses go on a credit card. That credit card balance earns 20%+ interest. Now a $1,500 car repair has cost you $2,000 by the time you pay it off, and you've added stress to your life that was entirely avoidable.
How Much Do You Need?
The standard recommendation is 3–6 months of expenses. Here's how to think about where on that spectrum you should land:
- 3 months: You have a stable job in a field with strong demand, a partner who also works, and few dependents. Your expenses are predictable and modest.
- 6 months: You're self-employed or work on commission, you have kids or other dependents, your industry is volatile, or your monthly expenses are high relative to your income.
Where Should You Keep It?
A high-yield savings account (HYSA). In 2023, these are earning 4–5% APY. Your money isn't "doing nothing" — it's earning a solid, risk-free return while staying liquid and accessible. Look for accounts at online banks like Ally, Marcus by Goldman Sachs, or American Express Savings.
How Do You Build It?
If starting from zero, set a realistic monthly savings target and automate it. Even $100/month gets you to $1,200 in a year, which is a start. As your income grows and your expenses are covered by your budget, increase the amount. Treat it like a bill — non-negotiable.
The One Risk: Inadequate Insurance
⚠️ The Risk: Not Protecting What You've Built
Insurance is financial bubble wrap. You spend years building a financial life — saving, investing, paying off debt — and inadequate insurance coverage can erase it all in a single event. The right insurance protection is the foundation of a resilient financial plan.
Nobody loves talking about insurance. It feels like betting against yourself. But I want to reframe it: insurance is what lets you take risks in life — start a business, buy a home, travel the world — knowing that if something goes wrong, you won't be financially destroyed.
The Coverage You Need to Review
Disability Insurance: This is the one most people overlook and the most important one to have. Your ability to earn income is your greatest financial asset. If you were injured or ill and couldn't work for 6 months — a year — could you maintain your lifestyle? Short-term disability is often provided by employers. Long-term disability, which kicks in after 90 days and can pay a portion of your income for years, is critical and often underfunded.
Life Insurance: If anyone depends on your income — a spouse, kids, even aging parents — you need life insurance. Term life insurance is simple and affordable for most young, healthy people. A 20- or 30-year term policy can provide significant protection for a surprisingly low monthly cost. If no one depends on your income, this may not be a priority yet.
Health Insurance: You know you need it. But are you maximizing it? Are you contributing to an HSA if you have a high-deductible plan? Are you using preventive care benefits? Don't just have coverage — understand it.
Renter's/Homeowner's Insurance: If you rent, renter's insurance is one of the best deals in personal finance. It typically costs $15–$25/month and covers your belongings against theft, fire, and other events. If you own, homeowner's insurance isn't optional — but make sure your coverage limits reflect the actual cost to rebuild your home.
Auto Insurance: Most people carry the legal minimum. Review your policy annually to make sure your coverage still makes sense for the age and value of your vehicle, and that your liability limits are adequate.
The Insurance Review Process
Don't just buy coverage and forget about it. I recommend reviewing your insurance needs once a year, and definitely when you have a major life change:
- New job (especially if it changes your employer-provided benefits)
- Marriage or divorce
- Having a child
- Buying a home
- Significant increase or decrease in income
- Reaching a major savings milestone
Why These Two Things First?
If you've been nodding along thinking, "Yes, but I also want to invest for retirement, pay off my student loans, save for a house, and fund my next big trip" — I get it. You should be doing all of those things.
But here's the financial planning truth: without an emergency fund and adequate insurance, everything else is fragile. Your investment portfolio can be wiped out by medical debt. Your retirement savings can be raided when an emergency hits and you have no cash. Your financial plan collapses like a house of cards.
The emergency fund and insurance are the foundation. Once they're in place, everything else you build on top of them is that much more secure — and the trip to Japan, the house, the retirement you actually want all become that much more achievable.
Not sure if your emergency fund is the right size or if your insurance coverage is adequate?
That's exactly the kind of conversation we have in our introductory call. Let's take a look at your full financial picture and make sure your foundation is solid before we build anything on top of it.
Schedule a Free ChatThe information provided in this article is for educational purposes only and does not constitute financial, legal, or tax advice. Please consult with a qualified professional before making financial decisions.